The case for climate realism in an age of soaring energy demand
- September 16, 2026
- Dieter Helm
- Themes: Economics, Energy, Environment
The conventional narrative assumes economies can grow while using less energy. The opposite is happening. It is time for climate realism.
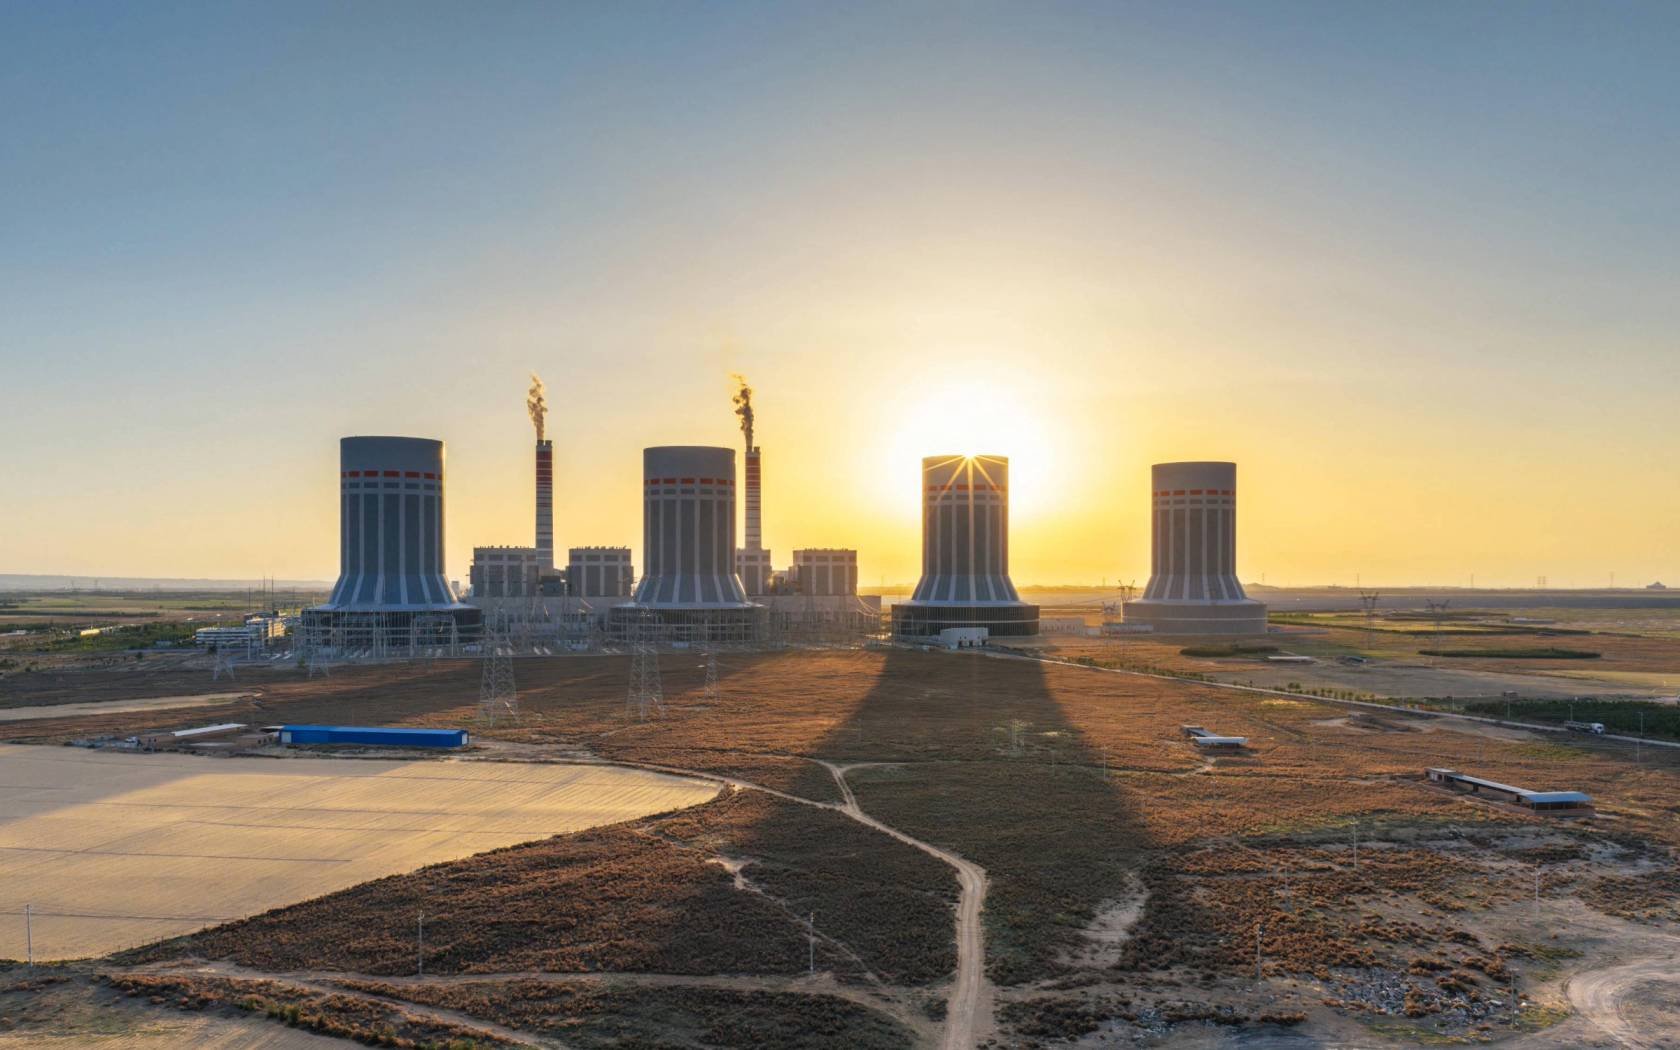
In the conventional narrative about decarbonisation, net zero is going to be achieved by building lots of wind farms and installing lots of solar; batteries are going to fix the intermittency problems when the sun does not shine and the wind does not blow; and it is all going to be cheap and can be delivered at sufficient scale to keep to the 2015 Paris Agreement target of well below 2°C of global warming. There would need to be a bit of gas, little or no coal, and, more recently, a good dose of nuclear, now added even by the greenest environmentalists. It would all be win-win-win – cheaper, more secure – and it would deal with climate change.
In reality, it will be none of these things. Countries such as the UK and Germany, which have pushed hardest for wind and solar, have some of the highest electricity costs in the developed world. Security of supply cannot be sufficiently guaranteed with short-term batteries, and the results have been more about deindustrialisation and territorial carbon production than about what really matters: carbon consumption. Made in China (primarily with coal) replaces Made in the UK or Made in Germany. The renewables supply chain dependency is now all about China, too, which produces around 80 per cent of the world’s solar panels and 80 per cent of the batteries and has a stranglehold on the refined critical minerals.
What makes all the above so deeply concerning is not just that it does not address why the concentration of carbon in the atmosphere has been marching up at around 2ppm a year since 1990, and now at nearly 3ppm. It also rests on a further assumption. The conventional narrative in the 1990s and beyond was that energy demand and GDP growth had decoupled. Economies could carry on expanding and at the same time use less and less energy – both in aggregate and in the intensity of energy in each unit of output.
For a period, this was indeed all true, but for a reason that was not highlighted in the conventional narrative. The reason the relationship between economic growth and energy demand broke down was in large measure due to changes in the composition of economies, and especially European ones. Global demand did not stop going up. Energy-intensive industries deserted Europe and boomed in China and Southeast Asia. Hence China emerged as the great polluter – and by far the greatest in emissions, even if some of these emissions are for us in Europe and especially in the UK. In the process, China became the largest coal burner – now with well over 50 per cent of the total global coal burn. As costs and prices of energy rose in Europe, new investments in energy-intensive production moved overseas.
It was not supposed to be like this. Energy efficiency was supposed to enable energy intensity per unit of output to fall. Energy efficiency was supposed to reduce the demand for energy and, as we approached the 2050 targets, new technologies would allow all those cheap renewables to overcome their intermittency.
This part of the narrative turns out to be wrong – and for two reasons, one theoretical and one about the changing economic composition of future economies. The theoretical reason is easy to state and devastating in puncturing the demand-side conventional narrative. If energy use is more efficient, it means less energy is needed per unit of output. This is equivalent to a fall in the price of energy. If price falls, demand goes up, not down. We can all consume more energy for the same budget. This is the Jevons paradox and it is rock solid. Energy efficiency improved massively in the 20th century and into this century, and it spurred a massive increase in the demand for energy.
To this is added a further blow: what we are now witnessing more generally across economies is a technology shift towards new energy-intensive industries not seen since the coming of steel in the late 19th century. These new technologies require lots of energy and they require it on a firm, not intermittent, basis. The energy they need is overwhelmingly electricity, and so electrification is rapidly advancing in those countries grasping the new economic opportunities and economic growth they may bring. That electricity is still generated overwhelmingly by fossil fuels (and fossil fuels still make up about 85 per cent of global energy supplies). Electric does not necessarily mean renewables, and intermittent generators like wind and solar do not meet the new AI industries’ demand for the five nines – electricity that is 99.999 per cent reliable.
The wider global implications of the spectacular growth of these new energy-intensive industries are yet to be fully understood. A little crude arithmetic illustrates the problem. Assume the global economy grows at three per cent a year. By 2050 on this assumption, the global economy will be twice its current size. Yet three per cent is well below recent historical standards, and below projected growth rates for China, India, Indonesia, Nigeria and much of Sub-Saharan Africa, Latin America, and indeed most of the world outside Europe.
Decarbonising two world economies, rather than one, in less than 25 years is a herculean task. It will be little short of a miracle if the existing one can be decarbonised, even if current policies continue. Since there is no blip in the continued increase in the concentration of carbon in the atmosphere, the sad fact is that we are not making progress on the existing one, let alone an additional one. The current policies are already under great pressure. Politically there is a revolt against even the costs so far, as the promise of UK and European cheap energy turns out to be a mirage. The great new AI and related digital technologies are not flocking to north-east Scotland to get access to its high-cost intermittent offshore wind. More widely across Europe, the story now is not about further decarbonisation of existing energy-intensive industries. That has already happened. What it is really all about is the relative lack of inward investment in these new technologies. It is plain to see that it is the US and China where the new industries are growing at scale.
There will be some inward investment, but not much compared with what Europe’s competitors attract. The reason is not only that firm power is what is needed, but also that electricity is very expensive in the UK and Germany, and more widely in Europe. Compared with Europe, energy is a quarter of the price in the US and about half the price in China. The great loss of competitiveness of Europe versus the US and China is not likely to dissipate any time soon. Nor are China, the US and now India going to radically decarbonise, which would be necessary in the scenario of a doubling of energy demand by 2050.
Some in the conventional climate paradigm think that China and India are going to lead the world to renewables and that these will be low carbon. It is true that China and indeed India are building lots of renewables. But the context and role of this wind and solar generation are poorly understood.
In China the load factors of the wind and solar can be as low as 20-25 per cent, so they are not generating for 75-80 per cent of the time. The huge building programme for firm coal-powered generation in China (and India) swamps their impacts. China has a coal-based electricity system, with a great nuclear build-out programme and huge expansion of its hydro dams in Tibet. Nuclear and hydro will make a difference, but this difference is relative not absolute. As the demand for energy keeps going up, the relative share of fossil fuels may fall, but the absolute burn levels may not. Even if the coal burn in China peaked and declined a bit, it would remain a global climate change disaster. Fossil-fuel absolute burn has to fall a lot, and in a scenario where the world economy doubles by 2050, this looks a very big ask. It is reasonable to assume, especially given the great growth in petrochemicals, that the world will still be burning at least 100 million barrels a day of oil in 2050, that it will be burning more gas than now, and that even if coal tails off a bit, there will still be a lot of coal generating electricity, used globally for industry and heating.
With a doubling of demand, it would be an incredible achievement if oil, coal and gas burns were lower than their current levels in 2050, and that would still commit us to a lot more global warming, and still breach the 2°C targets, possibly by a large margin. The share of fossil fuels may fall from 85 per cent, but if the world economy doubles, the aggregate burn would hold up even if the share halved, with all the terrible consequences for climate change. The greater the growth of the world economy, the more rapidly the share has to fall.
There is of course nothing inevitable about doubling the size of the world economy by 2050. It might not happen. But climate realism requires honesty about what would have to happen for world energy demand not to go up much. Wars in the 20th century were arguably stimuli to economic growth, so death and destruction as a result of conflicts between Russia (wanting to take back control of much of eastern Europe), China (wanting to take back control of Taiwan and much of east Asia) and the US (wanting to dominate the Gulf of Mexico, and take back control of Canada, Greenland and even Iceland) are not necessarily going to lead to a reduction in demand.
What about the AI and new tech and its incredible energy intensity? The new energy-intensive industrial revolution might not happen. It might be all hype. It might crash as the huge levels of debt and valuations prove to be no more than a tech-bro dream. But even if there is a tech crash, the technology is not going away. The Great Crash in 1929 did not stop the electricity rollout, and the dot-com crash did not halt the coming of social media.
The above setbacks are best seen as just possible temporary halts on the march of AI, in the context of a much bigger global economy. Another possibility is that these new technologies manage to use less energy than predicted. Perhaps they could get more energy efficient. They almost certainly would do so. But then along comes the Jevons paradox.
The above is all what I call ‘climate realism’. It is not optimistic or pessimistic. It’s just what is likely to happen. It has two radical implications: that we are going to have to adapt to a lot of climate change; and that if we want to mitigate climate change, in addition to all the current measures, economic growth and the associated consumption would have to be reconsidered.
Take the first one. There is very little chance of limiting climate change to 2°C and almost no chance of keeping it to 1.5°C. It’s just unrealistic, unless something really unlikely happens – large-scale manipulation of the atmosphere comes to mind, and that has serious downside risks, geopolitical as well as climatic. Sea levels are going to rise, as are peak temperatures.
This is not the end of the world. Lots of people live in high-temperature zones already. Air conditioning is now the norm in the richer parts of the world and essential in the Middle East. Desalination is already widespread and it will have to expand a lot. And so on. What is needed is to build infrastructure to match the temperature projections.
The second possibility is to address economic growth head on. This is what the ‘no-growthers’ argue. It is us and our consumption that cause all the data centres to be built. To use the title of Jean-Baptiste Fressoz’s book, we want More and More and More, and as a result we cause more and more pollution, because energy is the key ingredient of almost everything we want. We humans are going to consume our planet and its environment.
The argument is that this is all unsustainable, and hence it will not be sustained. This is probably correct. Economists assume that our preferences and consumption are insatiable; we will always want more. This is fine in theory provided all environmental and other externalities from our consumption are fully priced, and hence polluters really do pay. Theoretically, there is no necessary problem with economic growth, provided pollution is internalised and paid for. In other words, the right sort of growth is fine.
In practice, internalising pollution so that polluters pay is the exception, not the rule, and nowhere more than when it comes to the 85 per cent of global energy supply that fossil fuels provide, or the destruction of biodiversity by clearing rainforests and mining.
If we really wanted to internalise pollution and hence limit climate change, then it would go far beyond fossil fuels. Take renewables. Like almost everything else, they are based on mining, and a quick glance at aerial maps of mining areas for critical minerals, for copper, lithium, nickel and cobalt, speaks to their massive destructive activities and the scale and variety of the emissions they produce. Sadly, there is no such thing as clean energy. It is all dirty, just some is dirtier than others.
The reason why polluters are typically not forced to pay is that the polluters are ultimately you and me. Companies, large and small, do not produce stuff for the fun of it. They do it because it feeds our consumption. Climate reality is that we don’t want to pay for the pollution we cause. We want to live beyond our environmental means. We want ‘green’ energy, but we want it to be cheaper. If we really paid for the emissions embedded in the full supply chains of the energy we use, then it would have a big impact on our spending. We would be commensurately poorer. Over time new innovation may enable some sustainable growth, but the baseline would start a lot lower.
Recognising the awesome nature of the challenge in front of us may be frightening. People may want to close their ears. But ignoring the facts does not make it go away. Climate realism is the first step in rebasing climate policies, and facing up to what is likely to be coming. It is much more helpful than chanting mantras about ‘1.5°C’, ‘2°C’ and ‘net zero 2050’. It also tells us that adaptation is a very urgent need. Perhaps if the global population starts to fall at the end of the century and new technologies come along, it may all turn out well – eventually. But in the meantime, we face a doubling of energy demand by 2050, and that is much more likely to happen than limiting climate change to 2°C by then.
Dieter Helm



More from Energy

The war for oil never really went away

Britain’s energy transition in the shadow of the 1970s

Low power: how self-sufficient Sweden jeopardised its energy security

Why do politicians get energy policy wrong?


