SMRs: a short history of a nuclear pipe dream
- September 23, 2026
- Paul Josephson
Small modular reactors (SMRs) were first conceived for military use and deployed on polar bases. Seventy years on, their record remains dismal.
The nuclear industry has successfully commercialised nuclear power. The results are visible in some 440 nuclear reactors worldwide with a total of 400 GW in electrical energy capacity. Perhaps another 70 GW of capacity is under construction in 15 countries. In the last 15 years, nuclear powers have redoubled their efforts to secure multi-billion-dollar subsidies to deploy a long-time dream of the industry: small modular reactors (SMRs), including so-called microreactors that can be transported by aeroplane, hauled about by truck, or even dragged on sleds in the Arctic regions. The promised advantages of proposed SMRs include modular construction with units quickly assembled on site, lower costs and, for some of the more advanced designs, greater efficiencies thanks to higher operating temperatures. In theory, the designs are ‘inherently safe’, meaning reactors will shut down without human intervention in an accident situation.
SMRs are being pursued by several nuclear nations, including Russia, the United Kingdom, the US, Canada and China. At least 26 SMRs with a combined capacity of 2.9 GW have been announced in the US alone. There are two main approaches to the SMR. One is the effort of established nuclear leaders such as Rolls-Royce (the UK), Westinghouse, GE Hitachi, Rosatom and EDF (France) to build on 60 years of experience with PWRs (pressurised water reactors). The second is the effort of start-ups to pursue innovative designs with gas and liquid metal coolants, which, in fact, date to the dawn of the nuclear age.
While touted for addressing consumer demand for more electricity with safe, reliable and green civilian nuclear power, they are also being promoted as a way to meet the growing electricity needs of the burgeoning AI data centre sector. Yet SMRs remain unproven at scale, with only two operational worldwide. It will be decades, if ever, before SMRs come online in sufficient numbers to meet growing energy demand, while the capital costs remain cripplingly high.
The language of SMR promoters is intended to show that these reactors are a simple matter of deliver, unpack, plug in and operate. According to a United Kingdom government blog, ‘Companies are setting up assembly and test facilities to build standardised, off-the-shelf modules rather than constructing complex systems entirely on-site.’ The blog likens modules to factory production and assembling on site in industries such as ‘oil, gas and renewables… so why not nuclear power stations?’ But where are the factories to build standardised off-the-shelf 300-ton nuclear reactor vessels and their components?
The one attempt at factory production has been an abject failure. The Soviets opened the Atommash facility in Volgodonsk, Russia, from which reactor vessels would be shipped by barge and train to nuclear power plant (NPP) sites. Under construction from the mid-1970s, Atommash produced its first reactor in 1981, and then was closed after the collapse of a wall of its main foundry. Atommash, bankrupted by Chornobyl and the collapse of the Soviet Union, opened again in the mid-2000s with the direct intervention of Putin-era subsidies. Although Atommash was intended to produce eight pressure vessels annually, by 2017 only 14 in all had been manufactured, most of them in the 2000s.
None of this is especially new. SMRs were originally developed for military battlefield purposes. Military planners have experimented with SMRs for battle zones since the 1950s. Soldiers would assemble power plants brought to site in troop transports, or parachuted into combat zones in crates, or floated in on cargo ships. The head of the Soviet atomic bomb project, Igor Kurchatov, alluded to SMRs in a speech to the 20th Party Congress of the USSR in 1956. He imagined compact SMRs for Arctic use to assist in oil, gas and mineral exploitation, not just for military ends. SMRs were considered for use by the US merchant marine and by the Soviets on whalers; but fear that onboard accidents would make blubber highly radioactive put paid to those plans. Over 700 SMRs ultimately found a primary application in nuclear submarines in the US and USSR, and a smaller number in the UK, France and elsewhere, as well as for aircraft carriers and icebreakers. Only the state could absorb the enormous costs of these projects. But beyond nuclear submarines, there were few early SMR successes.
One early disaster was Camp Century (1959-67), a base tunnelled into the Greenland ice sheet and powered by a portable SMR hauled in on sleds. It was the testbed for Project Iceworm, a secret plan to hide hundreds of nuclear missiles under the ice, which was abandoned as unworkable. The reactor ran for less than three years, and its steel pipes and reactor vessel became radioactive. Dismantling the reactor in 1964 released still more radioactivity, while bulldozing snow to complete the disassembly released radioactive flakes of ice. That frozen waste material may now reappear due to global warming.
The first generation of stationary, portable (modular) and mobile (perhaps pulled in a truck trailer) SMRs left a lot to be desired, took longer to assemble than advertised, and all functioned poorly. One SMR, sent to power a naval base at Antarctica’s McMurdo Sound, ran on 20kg of enriched uranium, replacing millions of litres of diesel fuel that would have had to be shipped onto the ice. Yet malfunctions dogged the project, including poor operating quality and a cracked and leaking containment vessel. It was christened ‘Nukey Poo’ by the Antarctic contingent.
Russia is a pioneer in SMRs. Early versions originated in efforts to build nuclear submarines, icebreakers, freighters and other vessels. As in the US, there were also efforts to design small reactors for rockets, aeroplanes and locomotives, all of which, to this day, have suffered from extensive cost overruns, delays and poor operation (Russia has again embarked on a nuclear locomotive project under Vladimir Putin). In 1961 the USSR started up the TES-3, a mobile reactor carried on four tracked vehicles built on T-10 tank chassis. It worked, but was utterly impractical for any real use, and was shut down in 1965 after its first fuel load.
Another far-fetched mobile nuclear reactor was the Belarusian Pamir-630D, which was pulled along public streets on trailers. Dating to the mid-1960s, it was not tested until 1985. But the Chernobyl disaster and rising public fears prevented the Pamir from driving around Minsk, and its spent fuel was not removed for safe storage until the 2010s.
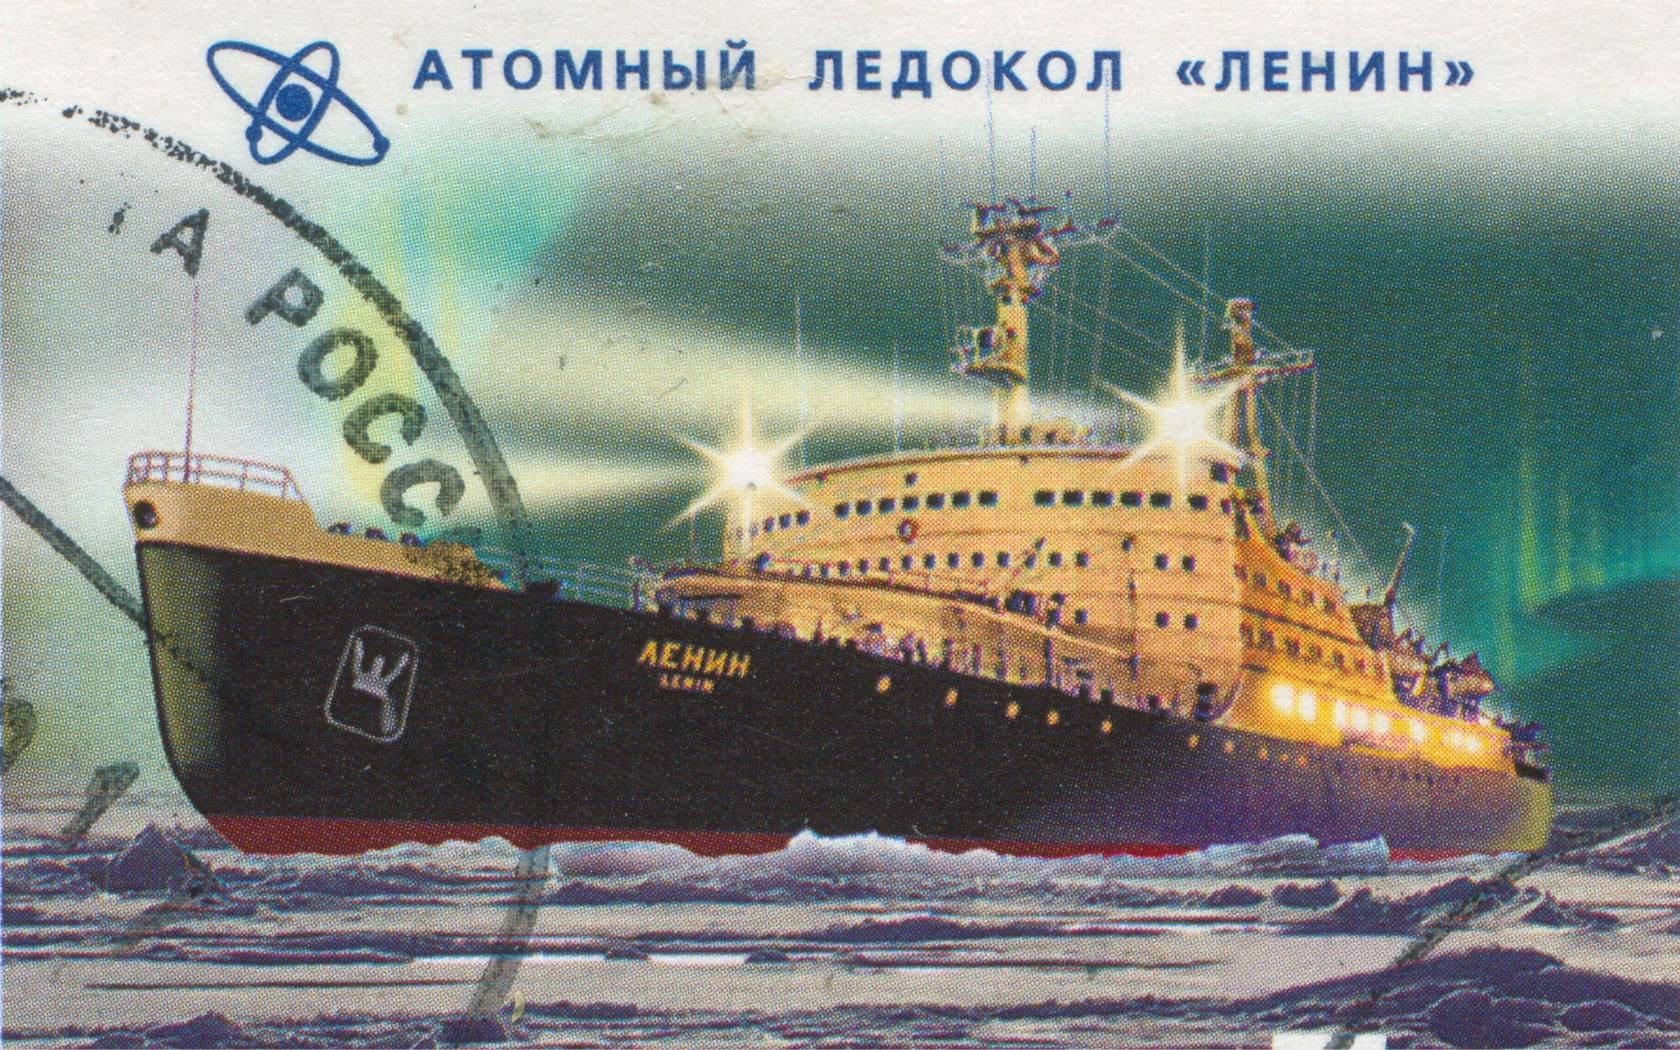
Nuclear icebreakers proved to be a major area of SMR focus and led to the development of fully-fledged floating SMRs. The Soviets launched the world’s first nuclear icebreaker, the Lenin, in December 1957; it entered service in 1959. It suffered two serious reactor accidents that released significant amounts of radioactivity and led to illegal dumping of wastes and reactor vessels at sea. In the 1960s and 1970s the Soviets deployed a series of icebreakers to claim ownership of the North Pole. Russia is modernising its icebreaker fleet to keep the Northern Sea Route open to commerce and to military ships, and so accelerate the assimilation of Arctic resources. The icebreakers will be powered by standard RITM-200 and –400 SMRs. The projects are notable for cost overruns and poor design, but when each one is commissioned the Kremlin dedicates it with great pomp and pride. Rosatom is building a two-unit land-based RITM-200 SMR in Uzbekistan.
The contemporary SMR industry is in its early stages with over 70 projects, with few approaching operation, more under construction, and many still in the design stage, at roughly $16 billion total. But, like the first military SMRs, they are running massively over budget. Nuclear power is far more expensive than solar and wind power, with its LCOE (levelised cost of electricity) estimated at $110/MWh in 2023 and forecast to remain the same up to 2050, while solar power was estimated to be $55/MWh in 2023 and expected to decline to $25/MWh in 2050. Onshore wind was $40/MWh in 2023 and expected to decline to $35/MWh in 2050. A study of 180 nuclear power plants (NPPs) around the world found that 175 of them exceeded the initial budget by an average of 117 per cent and took 64 per cent longer than projected. This is nothing out of the ordinary: nuclear forecasters have long been overly optimistic about costs. Data centres require round-the-clock power, but that does not in itself make the case for nuclear, still less for small reactors.
The nuclear industry has nevertheless pinned its hopes on SMRs because all recent large reactor projects have taken much longer to build and cost far more than originally projected. One of the first US projects completed this century, the Vogtle NPP in Georgia, was seven years late, $17 billion over budget, with electric customers being forced to pay billions of dollars before receiving any electricity. At the very least, the fact that in recent years the cost of a single 1,000 MW reactor has skyrocketed should give great pause to any decision to build a new reactor platform. How will SMRs be different?
Supporters claim that SMRs are ‘small’ and can be assembled rapidly, keeping costs down. Granted, a single SMR module takes up less room than a 1,000 MW reactor. But to make a plant competitive, developers typically group several units together: NuScale’s cancelled project planned six to 12, and four for Ontario’s Darlington SMR project. Thus, facilities are still massive, require an exclusion zone, and must be protected around the clock from intrusions – including by terrorists. Promoters claim they can put up an SMR ‘anytime, anywhere’ – as if space considerations have disappeared. That assertion flies in the face of the fact that only two SMRs are operating anywhere, one of which, a floating plant in Russia, took 13 years to bring online. As Atommash showed, there is still no factory that produces the components serially.
A major reason for the rebirth of interest in SMRs is the AI industry’s soaring demand for data-centre electricity. In January 2026, Meta announced plans to join with Vistra, TerraPower and Oklo ‘to boost the development of new advanced nuclear technology’ in the race to construct ‘superintelligence for everyone’. At the same time the Bezos Earth Fund announced a commitment ‘to help create a buyer “orderbook”’ for standardised, large-scale nuclear reactors in the United States. Peter Thiel’s Founders Fund has backed General Matter, a uranium enrichment start-up, which in January 2026 won a $900 million Department of Energy contract.
The efforts to power AI with SMRs reached their apogee in the TerraPower project, backed by Microsoft founder and philanthropist Bill Gates and by US government taxpayer money. Gates’ advanced 345 MW SMR, called Natrium, a sodium fast reactor destined for a site beside a retiring coal plant in Wyoming, is coupled with a molten salt integrated thermal battery. Gates is working with South Korean companies on supply chain agreements to support its manufacture. The NRC approved a construction permit for the reactor in March 2026. The project is receiving up to $2 billion from the Department of Energy. Not pressurised, the reactor is smaller than large PWRs, uses gravity and thermal convection for passive cooling, and ‘significantly reduc[es] safety-related costs compared to conventional reactors’.
In general, molten salt designs face serious problems. Because the hot liquid fuel and coolant salts quickly degrade standard metals at high operating temperatures (600°C to 700°C), such reactors require expensive specialised alloys; because nuclear fission products dissolve directly into the circulating liquid salt, the pumps, pipes and heat exchangers become extraordinarily radioactive; high residual radiation prevents humans from approaching components after shutdown, so that all repairs and maintenance must be done via remote-controlled robots. And there is no manufacturing industry for the right high-temperature and radiation-resistant parts.
Molten salt reactors have a poor record in any event. There was the infamous failure of a 15-year, $1 billion US Air Force project in the 1950s and 1960s to build nuclear-powered bomber aircraft that could stay aloft almost indefinitely without refuelling. An experimental 2.5 MW reactor built for the programme ran only briefly at Oak Ridge National Laboratory in 1954. Its successor, the Molten Salt Reactor Experiment of the late 1960s, required a new alloy to resist corrosion; the alloy handled corrosion, but not brittleness and cracking. According to one specialist: ‘These problems remain relevant. Even today, no material can perform satisfactorily in the high-radiation, high-temperature, and corrosive environment inside a molten salt reactor… In other words, 50 years after the molten salt reactor was shut down, technical experts still have questions about materials development for a new molten salt reactor design.’
Any real progress in bringing SMRs online will come, as it did during the Cold War, from the military. Wallets open, the US, Russian and other governments are determinedly subsidising military SMRs. In the US, the Pentagon’s Project Pele, a small, truck-mounted portable nuclear reactor that can be flown to remote locations and war zones, and powered up and down in days, moves forward. The goal was to deliver a full-scale prototype microreactor in 2024, to be followed by up to three years of testing at Idaho National Laboratory to validate its performance.
INL is the site of the 1961 explosion of an early SMR, the SL-1 prototype that killed three operators. Already three years behind schedule, Project Pele is being carried out by BWXT (earlier Babcock & Wilcox, dating to 19th-century boilers mnufacturers, which built nine commercial PWRs, including TMI unit 2, site of the partial meltdown). But the project will go forward, pushed on not by any fission, but by a White House executive order to deploy ‘advanced nuclear reactor technologies for national security’.
In addition to Pele, the Army’s Janus Program has awarded up to $2.2 billion to five companies to build microreactors at five bases, with more than 20 reactors envisaged across Defense Department installations. The first is due to operate by 2028. The contractors are Antares Nuclear, BWXT, General Atomics, Radiant Industries and Westinghouse. The Air Force is also pursuing portable reactors for three bases in Colorado, Montana and Texas.
The major nuclear nations have hopped on the SMR bandwagon, stationary or mobile. In spite of the poor historical record of SMR trials and failures, industry claims of impending success dominate public discourse. For example, in 2021, Rolls-Royce insisted that its SMR Consortium would generate 40,000 new skilled jobs, make a £100 billion contribution to the economy, and lead to the opening of a £400 billion global export market. The SMR programme would meet 2050 decarbonisation targets, with ‘an approximate doubling of the UK’s 9.5 GW existing nuclear capacity by 2030, then another doubling by 2050 to around 40 GW’. SMR salesmen claim that up to 100 470 MWe units would be sited around the UK, Sweden and elsewhere. With the first SMR at Wylfa on the Isle of Anglesey in North Wales not even close to construction, and with huge cost overruns and long delays in bringing the Hinkley Point C NPP online, it is difficult to imagine how SMRs can be built in the time frames and at the costs that Rolls-Royce advertises.
Canada, with 17 CANDU heavy water reactors, and another seven planned or under construction by 2040, and with huge uranium reserves, has two SMRs in process. Like the Americans and Soviets decades ago, Canadian Nuclear Laboratories (CNL) are pushing SMRs in remote Arctic communities to replace diesel power, in particular at mining sites. Nuclear officials claim that the nation’s first SMR project, four units of the GE Vernova Hitachi BWRX-300, will generate thousands of jobs, pour hundreds of millions of Canadian dollars into the economy, and secure a low-carbon future. They insist it will be assembled on site and have the footprint of a football field.
Drawing on uneven Soviet experience with mobile SMRs, Russia intends to develop self-propelled microreactors for the Russian military with outputs ranging from 100 to 1,000 kilowatts. In one version, the reactor will be mounted on a Kamaz truck chassis, a ubiquitous vehicle in Russia, or on a sled for use in Arctic conditions. The head of an engineering organisation for SMRs insists that serial production of the reactors will begin in the near future. With redoubled support from the Putin government, Russian engineers plan not only mobile military units, but reactors for deep space exploration, orbital launches, and even deep Arctic ocean natural gas tankers. Several Soviet Kosmos satellites with nuclear power packs fell back to earth, scattering radioactive debris.
Russia’s indefatigable Rosatom is most proud of its floating NPPs (Плавучая атомная электростанция, known by the acronym PATES in Russian). PATES can be adapted for heating, electricity, and/or desalination of water. Yet customers should beware that production problems have bedevilled the programme. The first PATES, the 70 MW ‘Akademik Lomonosov’, was three times over budget and years behind schedule. It operates at Pevek, in Chukotka on the eastern Arctic coast, moored in a bay. Rosatom apparently plans to build about a dozen PATES as the next step. Less than 20 years ago Russian specialists forecast that by 2030 they would have established year-round transport to strategic sites along the Northern Sea Route through the construction of no fewer than 40 new icebreakers and a handful of PATES, most fitted with RITM-200 SMRs, others destined for Uzbekistan, India, Kyrgyzstan and elsewhere. One domestic SMR scheduled for operation in 2028 may supply gold mining in Yakutia. Russian industry is 35 vessels behind target.
France’s nuclear programme, while committed to standard 1,000 MW and larger PWRs, has begun to consider designs for SMRs. Its SMR programme, still in a nascent stage, is directed toward carbon-free electricity, industrial heat, hydrogen production and potential export markets. The ‘France 2030’ €1 billion investment programme includes roughly €300 million specifically allocated to new modular reactor designs. The major SMR, Nuward, led by EDF, has already been redesigned once: in 2024 EDF abandoned its original twin-reactor 340 MWe concept, and is now developing a 400 MWe version built from proven technology, with a first unit in France targeted for the 2030s.
France has more novel approaches: Calogena is developing a pool-protected miniature reactor in Cadarache aimed at district heating; Stellaria is pursuing a fast-neutron molten salt reactor, also at Cadarache; Jimmy Energy & Blue Capsule are working toward industrial heat prototypes with a focus on a High-Temperature Gas-Cooled Reactor (HTGR); Newcleo is developing lead-cooled fast reactors (LFRs) of up to 200 MWe, designed to use spent nuclear fuel as a resource; and there is an India-France SMR/AMR Partnership.
China’s nuclear industry has supplanted that of the US as the most active. In its 14th Five-Year Plan (2021-25) it pledged 150 new reactors over the next 15 years, with a target capacity of 200 GW by 2035 – almost four times the current capacity. The impossible-to-reach target nevertheless indicates full commitment. China’s first SMR, a pebble-bed modular high-temperature gas-cooled (helium) reactor (HTR-PM) uses two ‘small’ reactors to drive a single 210 MWe turbine. Photographs of the site reveal clearly a massive structure; at $3 billion, it took ten years to come online. This Generation IV SMR in Shandong province produces much higher outlet temperatures (around 750°C) than a PWR. It is tailored for high-temperature industrial processes and chemical manufacturing, and is being used to provide heating for almost 2,000 households. A second SMR, the 125 MWe ACP100, or Linglong One, at Changjiang in Hainan, is due to come online in 2026. But at an estimated cost of 5 billion yuan (approx. $700–800 million), it has a higher per-megawatt cost than large-scale NPPs.
In March 2026, against this uncertain record, the European Commission (EC) adopted the same hubristic promises for European development of SMRs, calling them ‘innovative nuclear technologies that have the potential to contribute to the EU’s path towards climate neutrality, energy security and industrial competitiveness… SMRs could mobilise entire value chains across several EU countries and different sectors, and become one of Europe’s next major industrial development projects’. The EC makes the same unfounded claim that SMRs might be ‘manufactured in a factory setting and transported to site for immediate deployment or final assembly’. With none even under construction, and recognising their potential to power data centres, the EC estimates that ‘total SMR capacity in the EU could reach between 17 GW and 53 GW by 2050′. The Commission’s Nuclear Illustrative Programme (PINC), published alongside the strategy, puts total investment needed for EU countries’ nuclear ambitions at €241 billion by 2050.
The abandoned NuScale project reveals the false promise of SMRs. The only SMR design certified by the US Nuclear Regulatory Commission (NRC), it attracted more than $1.4 billion in federal cost-sharing support. The Idaho-based project was planned for 12 reactor modules producing a total of 720 megawatts. (The NuScale SMR power module measures approximately 76 feet tall by 15 feet wide and weighs around 700 tons.) Announced in 2015, the project soon saw costs skyrocket. It was scaled back to six SMRs to generate well under 500 MW. By 2023 the project was cancelled altogether as forecast costs rose 53 per cent from $58/MWh to $89/MWh, and overall from $5.3 to $9.3 billion, even before construction began. The price would have been much higher without $4 billion in federal tax subsidies and a $30/MWh break from the Inflation Reduction Act.
Promoters have been relatively silent about the risks that accompany ‘conventional’ NPPs that also hold for SMRs: safe transportation of nuclear fuel, long-term waste handling and storage, the disposition of spent nuclear fuel, hardened facilities to prevent a terrorist attack, and so on. Promoters also disingenuously claim that passive safety features should lead to reduced regulatory requirements; for example, approval for designs with fewer safety redundancies and waivers on emergency management plans. The aim is to speed licensing and lower costs, not to reflect any proof that SMRs are safer. The German nuclear safety agency noted that ‘based on the current state of knowledge it is not possible to state that a higher safety level is achieved by SMR concepts in principle’.
SMRs heighten the risk of terrorist attacks. A committee of the US National Academies of Sciences, Engineering and Medicine (NASEM) notes that SMRs would have high capital costs, technology gaps, and be neither portable enough nor powerful enough to meet the Army’s electric power requirements. They would enable proliferation, and surely offer a great target for terrorists as a ‘dirty bomb’. But concerns about safety, reliability and proliferation have not slowed SMR development, although SMRs have never gone beyond one-of-a-kind models and not one has come close to ‘off the shelf’ manufacture. Nuclear dreams remain, even if 70 years of high costs, one-off designs and technical underperformance indicate that they are a bad bet for investors.
Edwin Lyman of the US-based Union of Concerned Scientists has been asking pointed questions about SMRs for years. Could cost savings be realised by mass-producing major components as standard modules in factories, and shipping the modules to sites for assembly rather than having each reactor custom-designed and built? If the designs for SMRs are inherently safer, could they be located closer to densely populated areas than large reactors, even replacing coal-fired power plants at existing sites? Should the NRC relax certain safety regulations, for example, requirements for ten-mile emergency planning zones? It’s what the industry has spent decades pushing for. Big tech billionaires are pushing for accelerated licensing – and they have the ear of a friendly fan of nuclear power in the White House. Arnie Gundersen, a former nuclear industry executive, writes that the SMR is ‘a lose-lose: all the risks and headaches of traditional nuclear, but with none of the cost or scale advantages that never materialised in the first place’. He reminds us: ‘Consider that every steam generator ever built for US reactors has failed prematurely. Replacement generators have failed, too – sometimes within a year. SMRs will use the same technology, but somehow we’re supposed to believe the outcome will be different this time.’ SMRs will only be competitive in cost with wind, solar and other forms of energy when they are produced in sufficient numbers of standard models. And that is a nuclear pipe dream.
Given all this, the claims made for SMRs do not stand up to serious scrutiny. On the basis of no manufacturing experience and little operating experience, the industry claims that SMRs are more sustainable and more efficient than current NPPs. They remain, in fact, costly, with unique security problems, and with a large physical footprint. Neither military support, nor the interest of big AI, nor government subsidies justify thinking of them being able to hitch a ride on a huge vehicle to power a data centre, let alone join a combat mission.


